
J&K’s banking system is squeezed between rural duty, urban competition and a widening credit gap.
Every March, the numbers arrive dressed as good news. Deposits up. Advances up. Business crossing another lakh crore milestone. This year is no different: total banking business in Jammu and Kashmir touched Rs 3.48 lakh crore, growth of nearly ten per cent. Read the fine print, though, and the celebration curdles into something closer to alarm.
The credit deposit ratio, the truest measure of whether a region’s own money is financing its own economy, sits at 61 per cent, twenty points behind the national average, and has barely moved in two years. Jammu division alone lends out less than half of what it holds, an economy sitting on cash with nowhere obvious to put it. That is not thrift. It is a banking system failing to do the one thing it exists to do.
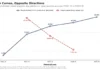
The deeper crisis is structural. Since Jammu and Kashmir became a Union Territory in 2019, national banks have arrived in hoards, but almost entirely in the cities. JK Bank still runs 62 per cent of its branches in the countryside; its newer competitors run barely 27 per cent of theirs there.
The arithmetic follows naturally: JK Bank has lost roughly twelve percentage points of the region’s lending market since 2019, even as it has kept its depositors almost without loss. The bank carrying the obligation of rural coverage is losing the profitable half of the business to lenders who never took on that obligation in the first place. The State Bank of India, flush with large ticket corporate and infrastructure lending that appears to bypass JK Bank almost entirely, looks the principal beneficiary.
Layered on top is a second, quieter strain. Priority sector lending, much of it low ticket, centrally sponsored credit that bureaucracy expects banks to disburse each year, grew more than ten times faster than ordinary commercial lending this year. Bank staff spend their days processing thousands of small, labour intensive loans, Mudra accounts averaging barely two lakh rupees, Kisan Credit Cards smaller still, while the commercial lending that actually signals a thriving local economy stall.
Asset quality, mercifully, improved this year. But bad debt remains concentrated in exactly the two cities, Srinagar and Jammu that carry the bulk of the region’s business, a warning that the clean-up is fragile rather than complete.
None of this is irreversible. But it needs naming plainly: a banking sector carrying the countryside on one shoulder and a shrinking urban franchise on the other cannot be called healthy simply because its deposit numbers keep climbing. Jammu and Kashmir does not have a shortage of money. It has a shortage of institutions willing to lend it out. Jammu Kashmir Bank needs to seize the opportunity and go public if it has any operational issue.