
by Malik Daniyal
Jammu and Kashmir’s 61 per cent credit-deposit ratio reveals a persistent capital outflow, underscoring structural lending barriers and the need for targeted reforms to channel savings into productive local investment.
 Every harvest season, the Valley’s press turns, almost reflexively, to the apple economy: highway blockades, price crashes, pest infestations, climate anomalies. These stories matter, but they have crowded out an arguably more consequential story that surfaced at the nineteenth meeting of the Union Territory Level Bankers’ Committee on August 1. Chief Secretary Atal Dulloo, while commending banks for disbursing a record Rs 84,384 crore in credit during 2025-26, flagged that Jammu and Kashmir’s Credit-Deposit ratio stands at 61 per cent.
This is a full twenty percentage points below the national average of roughly 81 per cent. He directed banks to prepare a time-bound roadmap to close that gap. The directive received a paragraph in most outlets and then vanished from public discussion. It deserves sustained scrutiny instead, because it describes a structural leakage at the heart of the region’s economy.
The Credit-Deposit ratio is a deceptively simple metric. It measures what proportion of the money a bank collects as deposits gets recycled back into loans within the same jurisdiction. A ratio of 61 per cent means that for every hundred rupees a Kashmiri household or trader parks in a savings account, fixed deposit, or current account, only sixty-one rupees returns to the local economy as credit. The remainder migrates outward, deployed as advances in Delhi, Mumbai or invested in government securities and instruments that carry no obligation to generate local employment or productive capacity.
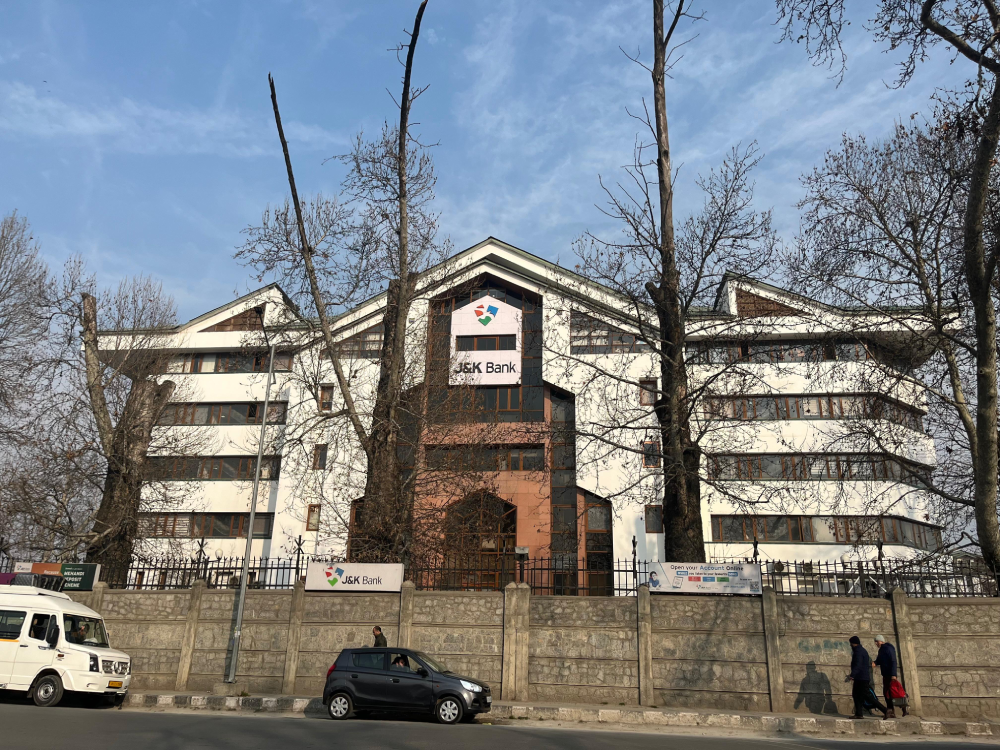
Jammu and Kashmir Bank, in which the government holds a 68 per cent stake, reported total deposits of Rs 1.73 lakh crore against gross advances of Rs 1.3 lakh crore in the quarter ending June 2026. A meaningful share of that lending book is deployed across Jammu, Kashmir, Ladakh and the rest of India collectively, rather than concentrated within the Valley’s productive sectors. This is, in essence, a silent transfer of capital away from a region that is chronically short of investment and toward economies that already enjoy deeper financial intermediation.
It would be a mistake to read this purely as negligence or malice on the part of banks. The proximate causes are structural, and understanding them is a precondition for fixing anything. Branch-level lending in Jammu and Kashmir carries a risk premium that lenders elsewhere do not price in. Decades of intermittent unrest have made loan officers understandably conservative, since asset seizure and recovery in the event of default remain more cumbersome here than in economies with settled land titles and predictable enforcement mechanisms.
Agricultural land, particularly orchard holdings that constitute the Valley’s single largest productive asset class, is often under-documented or encumbered by unresolved inheritance claims, making it a poor form of collateral even when its market value is substantial. Add to this a banking culture that has historically prioritised deposit mobilisation, which is safe, low-effort, and generates fee income, over local lending, which requires underwriting capacity that many branches simply do not possess. The result is a self-reinforcing equilibrium: deposits accumulate, credit stagnates, and capital that could finance cold storage units, agro-processing plants, tourism infrastructure or small manufacturing exits the region.
The government’s own messaging compounds the confusion rather than resolving it. Achieving 108 per cent of the Annual Credit Plan target sounds like an unambiguous success and officials have understandably celebrated it. But meeting a disbursement target is not the same as correcting a structural deficit in capital formation. A significant share of that Rs 84,384 crore likely comprises retail and consumption credit, personal loans, vehicle finance, and housing loans for salaried employees. These are the categories that do not build productive capacity or generate second-order employment.
Of the total, Rs 44,228 crore was classified as priority sector lending, with J&K Bank alone contributing over 63 per cent of it. That is commendable on its own terms, but priority sector classification is a regulatory category and not a guarantee that the underlying assets are the kind that compound value over time, such as processing infrastructure or export-oriented manufacturing. Celebrating target achievement while the CD ratio stagnates around 61 per cent, a level that has barely moved in years despite repeated official acknowledgement, suggests the two conversations are happening in parallel rather than in dialogue with each other.
What would a genuine correction look like? Four measures merit serious consideration, none of which requires reinventing the wheel, since precedents exist elsewhere in the country.
First, the administration should establish a dedicated J&K Credit Guarantee Fund, modelled loosely on the Credit Guarantee Fund Trust for Micro and Small Enterprises but calibrated to the specific collateral gaps of horticulture, handicrafts and tourism. If branch managers are indemnified against a defined share of default risk on qualifying local loans, the personal and institutional incentive to under-lend diminishes considerably. Risk aversion is rational behaviour under the current incentive structure; changing the structure, not merely exhorting bankers to lend more, is what will shift outcomes.
Second, district-wise Credit-Deposit ratios should be published quarterly and made publicly accessible, rather than surfacing only inside UTLBC minutes once or twice a year. Transparency of this kind functions as a low-cost accountability mechanism. Legislators, civil society and business chambers cannot press for corrective action on a number they never see.
Third, the government should explore linking its own treasury and public sector deposits, which form a substantial share of the deposit base held with J&K Bank, to explicit local lending covenants. This is an approach that some State Level Bankers’ Committees elsewhere in the country have used to nudge lending behaviour without resorting to statutory compulsion.
Fourth, and most foundational, land record digitisation should be accelerated specifically with an eye toward converting orchard and agricultural holdings into bankable collateral. This connects the finance conversation back to the horticulture sector that dominates headlines, but from an entirely different angle: not subsidies for high-density plantation, which the government already offers generously, but the legal and administrative scaffolding that would let a Shopian orchardist actually borrow against the asset he owns.
None of this is a rejection of what the banking sector has achieved. Record disbursement and historic priority sector performance are genuine accomplishments and officials are right to note them. But an economy cannot be said to be financially healthy simply because it meets annual targets set in advance. The deeper test is whether the money residents entrust to banks circulates back into the ventures, farms and enterprises that could employ them.
On that test, Jammu and Kashmir remains a net exporter of capital it cannot afford to lose. The Chief Secretary was right to name the problem publicly. What happens next, whether the promised roadmap produces measurable movement in the ratio or fades into the next quarter’s talking points, is the story worth following long after this apple season has ended.
(Malik Daniyal is an economics graduate from Delhi University. Ideas are personal.)